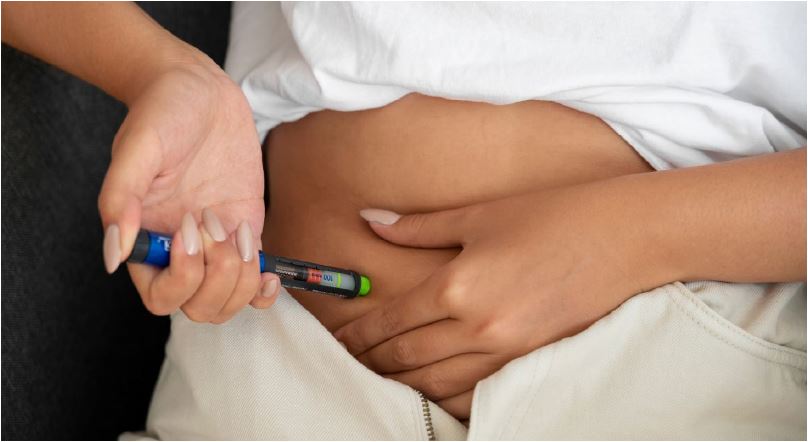
A motion for certification of a class action was filed against Clal Insurance and Finance claiming that its interpretation regarding the replacement of a weight-loss medication for insureds under a health policy is contrary to law. Likewise is the company’s refusal to indemnify insureds for replacing the drug. The applicant notes that he is among the employees of a company whom Clal insured under a group health policy. This policy included, subject to certain conditions being met, insurance coverage for a “drug for weight loss purposes”. According to him, Clal approved his claim for indemnity for a specific drug prescribed to him for weight loss purposes. Following a significant increase of approximately 30 kg in his weight due to taking psychiatric medications, the attending physician prescribed him the medication for obesity treatment Wegovy. Clal approved his claim for indemnity in accordance with the policy terms. Treatment with this drug led to a decrease of approximately 15 kg in his weight. However, after about a year and after reaching the maximum dosage, the drug’s efficacy diminished, and for many months taking it did not lead to any decrease in his weight. Due to this, the attending physician recommended that he replace the drug with the equivalent drug Mounjaro, which is also intended for obesity treatment. However, according to him, Clal refused to approve his claim for indemnity for the alternative drug, claiming that he purportedly does not meet the conditions of the exception to the exclusion in the policy. The exception stated: “The BMI ratio correct as of the date of need for the drug does not meet the condition of the exception, which is a BMI ratio higher than 30 and the insured suffers from a chronic illness, or a ratio higher than 36 without risk factors”. In the motion filed with the Central-Lod District Court, it was stated that according to the applicant’s approach, the rejection of the applicant’s claim for indemnity for the drug Mounjaro rests on three claims that reflect an essentially erroneous fundamental position of Clal regarding the correct interpretation of the policy. First, according to Clal’s approach, once the insured requests coverage for a drug different from the drug initially approved for him, even if it is a drug identical to the first drug approved, it is purportedly a new insurance event, and the applicant must once again meet the eligibility conditions under the policy. Second, according to Clal’s approach, the relevant date for examining whether the insured meets the eligibility conditions under the policy is the date of need for the new drug and not the date of need for the original drug, when the insured began the treatment intended to provide a response to the qualifying medical condition under the policy. Third, according to Clal’s approach, the panic disorder from which the insured suffers and due to which he takes psychiatric medications that lead to an increase in his weight, does not constitute a “chronic illness” as defined in the policy. According to the applicant’s claim, Clal’s said position contradicts the policy and contradicts the law. Furthermore, the circumstances in which an insured is required to replace one weight-loss drug with another weight-loss drug within the framework of treatment in a case amounting to an “insurance event” are common and frequent. Therefore, Clal’s fundamental position that led to the rejection of his claim regarding the second drug is shared by many other insureds. From Clal Insurance and Finance it was stated: “The motion has not yet been received by the company. When received, we will respond in the customary judicial instances”.
Motion for class action against Clal claiming it does not approve replacement of weight-loss medication for an insured under a health policy
The applicant claims that after approving treatment with the drug Wegovy for him, Clal refused to approve his claim for indemnity for an alternative drug * It is claimed that according to Clal's approach, switching to a new drug is a new insurance event and the applicant must once again meet the eligibility conditions under the policy
 By Editorial