
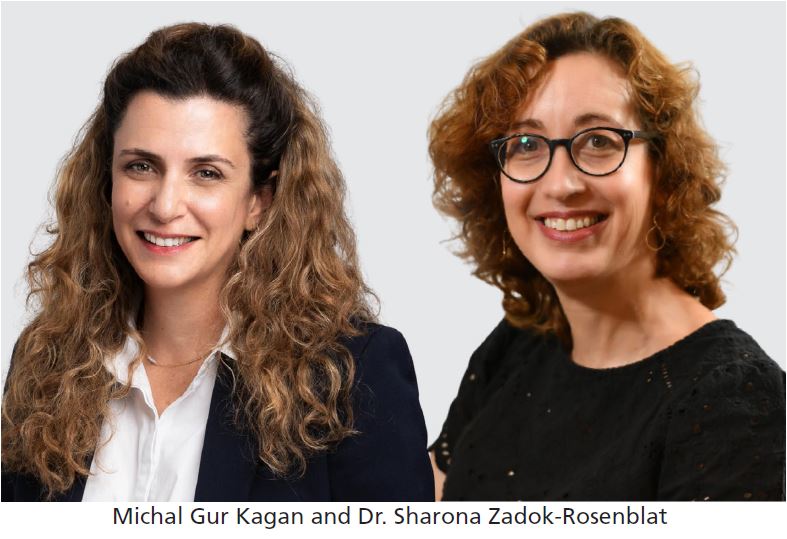
The National Economic Council in the Prime Minister’s Office published in September 2026 an outline for mandatory pension reform. According to the outline, the employee’s contribution obligation, which currently stands at 6% of salary, will be cancelled until age 40. The declared goal is to increase the disposable income of young households during the years in which they spend a lot on raising children and purchasing an apartment. A new position paper written by Michal Gur Kagan, Head of the Pension and Savings Field at the Phoenix Institute, and Dr. Sharona Zadok-Rosenblat, CPA, states that the outline in its current format “raises a number of fundamental difficulties.” The position paper states that the heaviest argument against the reform is the calculation itself. Assuming an average real return of 4.5%, a Shekel deposited at age 25 accrues return for 42 years and grows by 6 times until retirement. A Shekel deposited at age 50 grows by only 2 times. According to the authors, deposits at a young age are what generate most of the final allowance. Canceling them will harm the “primary growth engine of savings.”
Yesterday’s labor market
The authors note that the outline assumes that the labor market will continue to operate as in the past: the same employment rate, the same salary level, and the same entry and exit age. They refer to a 2025 World Bank study, according to which artificial intelligence is already affecting high-salary professions and making entry difficult for starting employees, especially in high-tech. “Is it right to harm future income from pension in a period when employees are able to deposit?”, they ask.
For further reading on the subject:
* Separating operations from investments and insurance: Adv. Tal Hafling with a revolutionary proposal for decentralizing the Israeli pension system
* Dafna Kaufman, pension, life and health insurance actuary: Reducing pension deposits could lower the allowance from 50% to 42% of salary on the eve of retirement
* The proposal to reduce the deposit to pension | Collateral damage: When the public suffers from low pension literacy I am worried. When economics experts suffer from it I am very troubled | Yoram Leviant, Chairman of the Pension Insurance and Finance Committee at the Chamber of Insurance Agents
* The Chamber of Insurance Agents responds to Prof. Avi Simhon: Demanding that any change in the pension model be made only after examining its impact on the allowance, insurance coverage and economic security
The authors also criticize the methodology: The outline relies on one alternative from one study that has not yet been published, and presents few sensitivity analyses. According to the paper, the amounts are presented in 2022 prices and are not discounted according to the price index forecast. In addition, the high replacement rate presented for the bottom quintile (1.69) stems mainly from very low income on the eve of retirement. A pension of 6,600 Shekels, the researchers write, “is not expected to be a pension that enables a life of dignity.” The same reservation applies, according to them, to the improved replacement rate presented for women. According to the position paper, the outline assumes that after age 40 household expenses decrease, but does not present an empirical basis for this. In practice, at ages 40 to 60 many families are at the peak of expenses: they fund studies, weddings, and apartments for children, and simultaneously support aging parents. Beyond that, after age 50 employment stability declines and the risk of prolonged unemployment rises. The authors also warn of harm to the actuarial and demographic balance mechanism of pension funds. If deposits are reduced by default, the burden may shift to members who continue to deposit at the full rate. As an example, they bring the group long-term care insurance: 2016 regulations obligated HMOs to accept insureds aged 60 and older without medical underwriting, and according to the paper, the violation of the mutual balance contributed to destabilizing the model. The paper presents an opposite trend worldwide. Australia gradually increased employers’ contribution obligation from 9.5% to 12% in July 2025. The OECD explicitly warns against mechanisms that allow postponing or reducing contributions at a young age. In the US, according to the OECD, voluntary occupational plans covered in 2021 only 37.4% of people aged 15 to 64.
Four alternatives
The authors agree that young families need to be assisted, and suggest four directions for examination:
1. Credit points and early childhood education: Expanding credit points for young parents and subsidizing daycares and after-school care centers, in the spirit of the 2011 Trajtenberg Committee report.
2.Senior citizen allowance: Moving to a progressive allowance, similar to negative income tax, that will compensate the bottom quintiles in a targeted manner.
3.Tax incentives: Increasing tax benefits for deposits of low-income earners, including “reverse brackets.” According to the paper, the model can be built so that the budgetary cost will be zero.
4.Graduated deposit: 1% to 2% at the beginning of the career, and a gradual increase with age, perhaps also beyond 6%. In this way the savings habit is preserved, but according to the authors this model also requires sensitivity analyses due to the loss of return. The authors emphasize that the alternatives are preliminary policy directions that have not undergone evaluation. Their conclusion: any reform in pension must be examined “thoroughly and systematically,” comparing several alternatives and including comprehensive sensitivity analyses, before formulating policy.
