



A Commissioner’s position prohibiting discrimination based on geographic location of insureds and insurance applicants in auto insurance was published today (Tue.) by the Capital Market Authority. The Authority clarifies that a discriminatory practice based on address and residential area is improper and prohibited by law. The position is published against the backdrop of cases showing that insurance applicants in auto insurance lines were discriminated against solely based on their place of residence and following the conclusion of the review of public comments on the draft published on the subject in early 2025. The current position is published at the conclusion of an orderly process in which all comments submitted on the draft published on the subject were reviewed. The Authority addressed the matter after cases reached its doorstep involving insurance applicants who were refused during the underwriting process based on their place of residence alone, in the absence of statistical basis, and without other parameters being examined. In other cases, it became known that “strict underwriting” was conducted for insurance applicants, at times including requirements that cannot be implemented and constitute a barrier to purchasing insurance. The cases occurred in relation to several geographic areas, with an emphasis on peripheral localities. Key points of the Commissioner’s position:
* Residential address alone will not constitute a parameter in an underwriting process: It is prohibited to refuse to insure in auto insurance based on residential address, and this parameter can no longer be used.
* Prohibition of conducting “strict underwriting” around the matter of residence for insurance applicants: It is prohibited to perform a procedure in the framework of which an insurance applicant in auto insurance is required to present additional certificates based on their residential address.
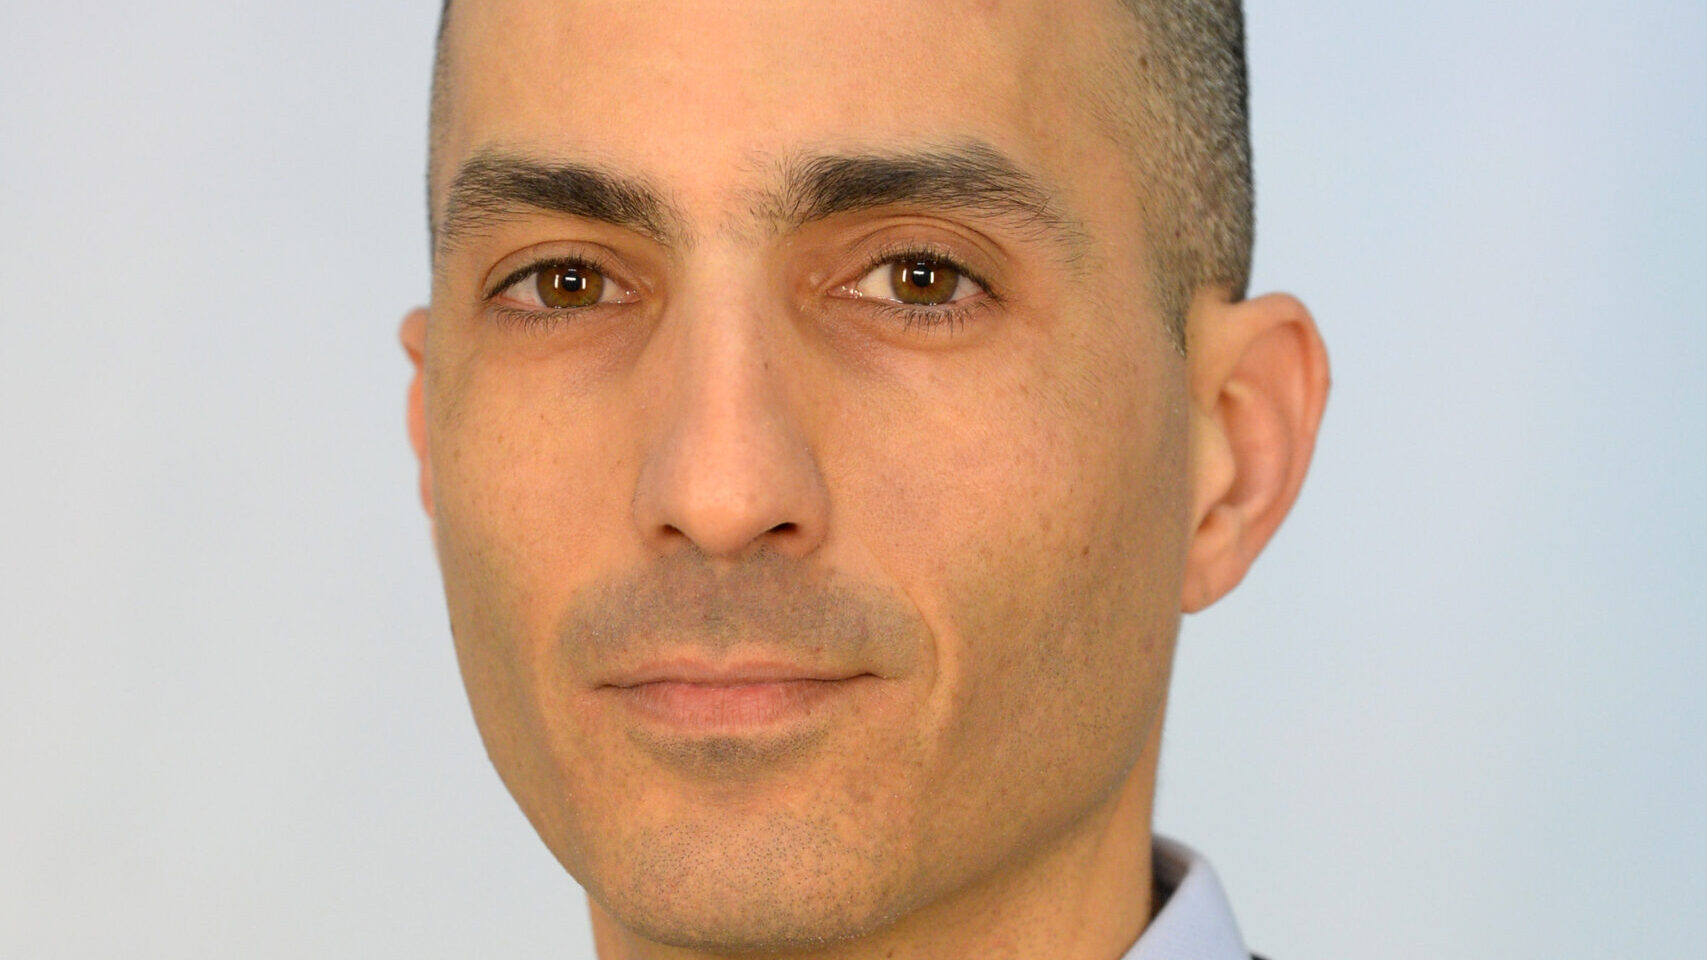
* Prohibition on pricing based on geographic area: This prohibition will apply as long as the insurance company has not proven, through statistical studies, that the level of insurance risk is affected by one geographic area or another. Amit Gal, Commissioner of the Capital Market: “The Capital Market Authority is committed to promoting regulation based on a consumer perspective, and to ensuring equality and fairness in the purchase of insurance by the public. The position is intended to ensure that insureds and insurance applicants in auto insurance will no longer be discriminated against based on their place of residence, and that every person will be given full availability of insurance, and the option to choose the product best suited for them. The publication of the position is based on complaints that reached the Authority, and are now translated into actual regulation in a manner that best illustrates the importance of the close relationship between the Authority and the public.” The Chamber of Insurance Agents stated in response: “The Chamber of Insurance Agents in Israel clarifies that it opposes geographic discrimination in auto insurance based on zip code, and that the struggle on the subject began back in the previous term of the Chamber led by President Shlomo Aizik. The Chamber’s position is clear: the use of residential address must not be allowed as a substitute for distinction based on nationality, sector, or social affiliation. “Insurance companies are entitled to manage risks and establish professional criteria for underwriting. But the criteria must be pertinent, data-based, and egalitarian. When insureds with similar driving and insurance characteristics receive different treatment due to their residential address, a real concern arises that the geographic consideration is used as a cover for discrimination,” the Chamber stated. The Chamber emphasizes that the harm does not end with insureds who are denied equal access to insurance. The phenomenon also harms competition and the insurance agents serving those populations.


